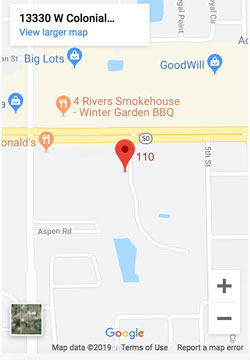
Main Office
13330 W Colonial Drive Suite 110, Winter Garden, FL 34787
Phone: (407) 982-4321
Two closings, one day, and money that has to move in exactly the right order. Whether you’re a wholesaler running a double closing or a homeowner selling one house and buying the next, Legal Counsel, P.A. structures simultaneous closings in Orlando so they actually close.
There are several types of simultaneous closings, and the one real estate investors ask about most is the double closing. An investor or wholesaler finds a good deal, contracts to buy the property from the original seller, and then sells it the same day to an end buyer who is willing to pay more. Because the intermediary is party B between seller A and buyer C, this is also called an A to B to C closing, a double close, or a back-to-back closing.
Each leg is a separate, complete real estate transaction with its own closing costs. In the first transaction, the wholesaler agrees to purchase the property from the original seller at the contract price. In the second, minutes or hours later, the wholesaler agrees to sell the property to the final buyer at a higher price and keeps the difference. Two deeds are recorded, two closing statements are prepared, and the title company or closing agent has to run both files in the right sequence.
The alternative in wholesale real estate is to assign the purchase contract to the end buyer for an assignment fee. An assignment is cheaper and simpler, but it exposes the wholesaler’s profit margin to both sides, and a seller who learns the buyer is flipping the contract for a large spread sometimes walks.
A double closing involves two separate transactions, so it keeps each one private: the final buyer never sees what the wholesaler paid and the original seller never sees what the final buyer paid. That difference between the two methods is the whole reason experienced real estate investors put up with the extra cost.
A double close real estate strategy also solves the problem of contracts that aren’t assignable at all. Bank-owned and institutional sellers commonly prohibit assignment, and some add resale restrictions on top. If you want to wholesale deals from those sellers, taking title and reselling is the only path, and it has to be done correctly.
The catch is that the first leg has to fund before the second one does. Title insurance underwriters in Florida generally won’t allow the final buyer’s money to pay for the intermediary’s purchase, so the investor needs its own funds or transactional funding, a short-term loan, often for a single day, that covers the A to B purchase price and is repaid out of the B to C proceeds.
Transactional lenders, often the same hard money lenders investors already use, charge a percentage of the loan plus a fee, so the cost comes straight off the spread.
Each stage has to be carefully documented, with the money changing hands in the right order and each deed recorded at the right time, and both legs have to occur on the same day or the numbers stop working. Under Florida law, documentary stamp tax is due on each deed at the state rate on the full consideration, so a double closing pays it twice, and any new mortgage on the end buyer’s side carries its own tax. Those costs have to be in the numbers before you commit.
Double closings are legal in Florida. There is no prohibition on buying property and immediately reselling it, and an investor who takes ownership of the property is acting as a principal, not as a real estate agent.
The risk is in what happens before the closing: marketing a property you don’t own, or don’t hold a contract on, to a buyer for a fee can be treated as unlicensed brokerage under Florida’s real estate license law, and the Department of Business and Professional Regulation pursues it. A properly drafted purchase and sale contract that gives you an equitable interest, marketed as your contract rather than the seller’s property, is what keeps a real estate wholesaling business inside the line.
Investors and wholesalers wanting to complete simultaneous closings in Florida should talk to a lawyer who handles them regularly. Legal Counsel, P.A. employs simultaneous closing lawyers in Orlando, Florida, and a real estate attorney who has run these before will draft the purchase and resale contracts, coordinate the transactional funding and the title work, and review the transaction so you don’t encounter a problem at the closing table.
Call Legal Counsel, P.A. at 407-982-4321 for a free consultation, or send us
the deal online and we’ll tell you how it should be structured.
The other situation where people run into a simultaneous closing real estate contract is a homeowner who is selling their current home and buying another one. This is also called a concurrent closing.
If you’re moving to a new home or a new area but you already own a house, the first question is whether it makes sense to sell before you buy. That question gets harder when you have a mortgage on the current home and need a new mortgage on the next one, because most lenders won’t approve the second loan while the first is still outstanding.
The usual answer is a contract structured around a concurrent closing, where you sell one home and purchase the new one back to back, often at the same closing table on the same day. The proceeds from the sale fund the purchase, the old mortgage is paid off, the new one is recorded, and you move once.
Many homeowners choose to sell first and then buy, because it’s the lowest-risk order. You only commit to the second home once you have a sure price on the first. Buying first and then selling puts you in a bind if the old home fails to sell at the expected price, and lenders may not extend a second mortgage while the first is still on your credit.
When you sell first, you have the option of a concurrent closing clause in the sales contract, which makes your obligation to close on the sale contingent on finding your next home. If you plan to use it, think about your buyer’s timeline and whether you can realistically find a new home inside the contingency period, which usually gives you only a set number of days. Some sellers skip the contingency, close, and rent for a few months while they search.
Concurrent closing same day arrangements aren’t the only option. Some lenders offer a bridge loan at a higher interest rate if you don’t want a contingent contract, or if you’re buying in a market where a contingent offer won’t compete. A home equity line on the current home can serve the same purpose.
In many cases, though, if you’re selling a home you already own and buying the next one, a simultaneous closing is the cleanest route, and our Orlando simultaneous closings lawyers draft the contracts, explain your rights and obligations, and handle the sale and the purchase from start to finish.
Simultaneous closings are timing problems dressed up as real estate transactions, and the firm that handles both closings is the one that can keep them in step. Michele Diglio-Benkiran founded the firm and has practiced business and real estate law since 1999, and investor and wholesaler work has been part of the practice for years, alongside title insurance, escrow and land trust services for the same clients.
Richard Sierra brings more than three decades of commercial litigation experience, which is a useful thing to have behind a contract when a deal starts to wobble.
Results matter to us, and so does a closing that happens on the day it’s supposed to. We offer a free consultation, and pay later options are available for clients who qualify.
We handle simultaneous and double closings for investors, wholesalers and homeowners throughout Orlando and Orange County, and across Central Florida from our Winter Garden, Orlando and Seminole offices, including Seminole, Osceola, Lake and Polk counties. Simultaneous closings are one part of our real estate services for investors and wholesalers, which also cover escrow, title insurance, property research and Florida land trusts.
A double closing lives or dies on the paperwork and the funding sequence. Let us structure
it before the closing date is set; the consultation is free.
A double closing real estate transaction is two back-to-back closings on the same property, usually the same day. An intermediary buys from the original seller in the first closing and sells to an end buyer in the second, keeping the difference in price. It’s the wholesaler’s alternative to assigning the contract.
Yes, in Florida. Buying a property and immediately reselling it is lawful, and each closing is a normal, fully documented transaction with its own deed, closing statement and taxes. What isn’t lawful is marketing property you neither own nor hold under contract for a fee, which can be unlicensed brokerage.
The wholesaler signs a purchase contract with the seller and a separate sale contract with the end buyer, arranges funding for the first purchase, and schedules both closings with the same title company or closing attorney. The first closing funds and records, then the second closing funds, the transactional loan is repaid, and the wholesaler receives the spread.
In an assignment, the wholesaler never owns the property; it sells its original contract to the buyer for a fee through an assignment contract, and both parties see the fee. In a double close, the wholesaler takes title and resells, the profit stays private, and the method works on contracts that can’t be assigned. The trade-off is two sets of closing costs and the need for funding.
A short-term loan, often for a single day, that funds the wholesaler’s purchase in the first closing and is repaid from the second closing. Lenders typically charge a percentage of the amount borrowed plus a flat fee, and they approve based on the two signed contracts rather than the borrower’s credit. Approval can be quick once the contracts and title commitment are in hand.
Generally not. Using the end buyer’s funds to pay the original seller, sometimes called a dry closing, is prohibited by most Florida title underwriters, and a closing agent who allows it risks the policy. Plan on your own funds or transactional funding.
Then the wholesaler owns the property, with the transactional loan due. That’s the real risk of a double closing, and it’s why the end buyer’s contract should be signed, funded and cleared through title before the first closing is scheduled. We build the contracts so the second leg is as certain as it can be before the first one funds.
Not to buy and resell a real estate property you take title to; that’s acting as a principal. You can cross into licensed activity by advertising the property itself to buyers before you own it or hold it under contract. Market your contract, not the seller’s house, and have the contract drafted so your equitable interest is clear.
Yes. Florida charges documentary stamp tax on each deed based on the consideration paid, so the A to B deed and the B to C deed each carry it, and a new mortgage on the end buyer’s side adds tax on the note. Those numbers belong in the deal analysis from the start.
Often, yes. FHA and some conventional programs restrict financing on properties resold within a short period after the seller acquired them, and most lenders want to see that the seller is on title. Cash buyers and hard money lenders are the usual end buyers in a double close for that reason, and we confirm the end buyer’s financing before the closings are set.
Selling your current home and buying the next one back to back, usually on the same day, so the proceeds from the sale fund the purchase. The contracts are written so the two closings depend on each other, and a lawyer coordinates the payoff of the old mortgage and the recording of the new one.
You may need a short-term rental or a post-closing occupancy agreement that lets you stay in the sold home for a few days. That agreement should be in writing before the sale closes, with the rent and the liability spelled out, and it’s one of the things we negotiate when we set up a concurrent closing.
Yes, and it’s usually the better arrangement, because one office controls the sequence, the wires and the recording. For a double closing in particular, a closing agent unfamiliar with A to B to C transactions is the most common reason they fall apart.
Whether you’re an investor looking to wholesale real estate or a homeowner who needs to sell and buy on the same day, a simultaneous closing rewards preparation and punishes improvisation. Call Legal Counsel, P.A. at 407-982-4321 or use our contact form to schedule your free consultation.

WE VALUE RELATIONSHIPS
Most of our clients come to us by referral and word of mouth (not advertising).

COMMITMENT TO EXCELLENCE
The Legal Counsel team is committed to serving all clients with excellence and professionalism.

EXPERIENCE MATTERS
Decades of Representation.

CUTTING EDGE TECHNOLOGY
View your entire case, communicate with us 24/7, review billing statements, documents, etc. on our bank secure, online client portal.